-
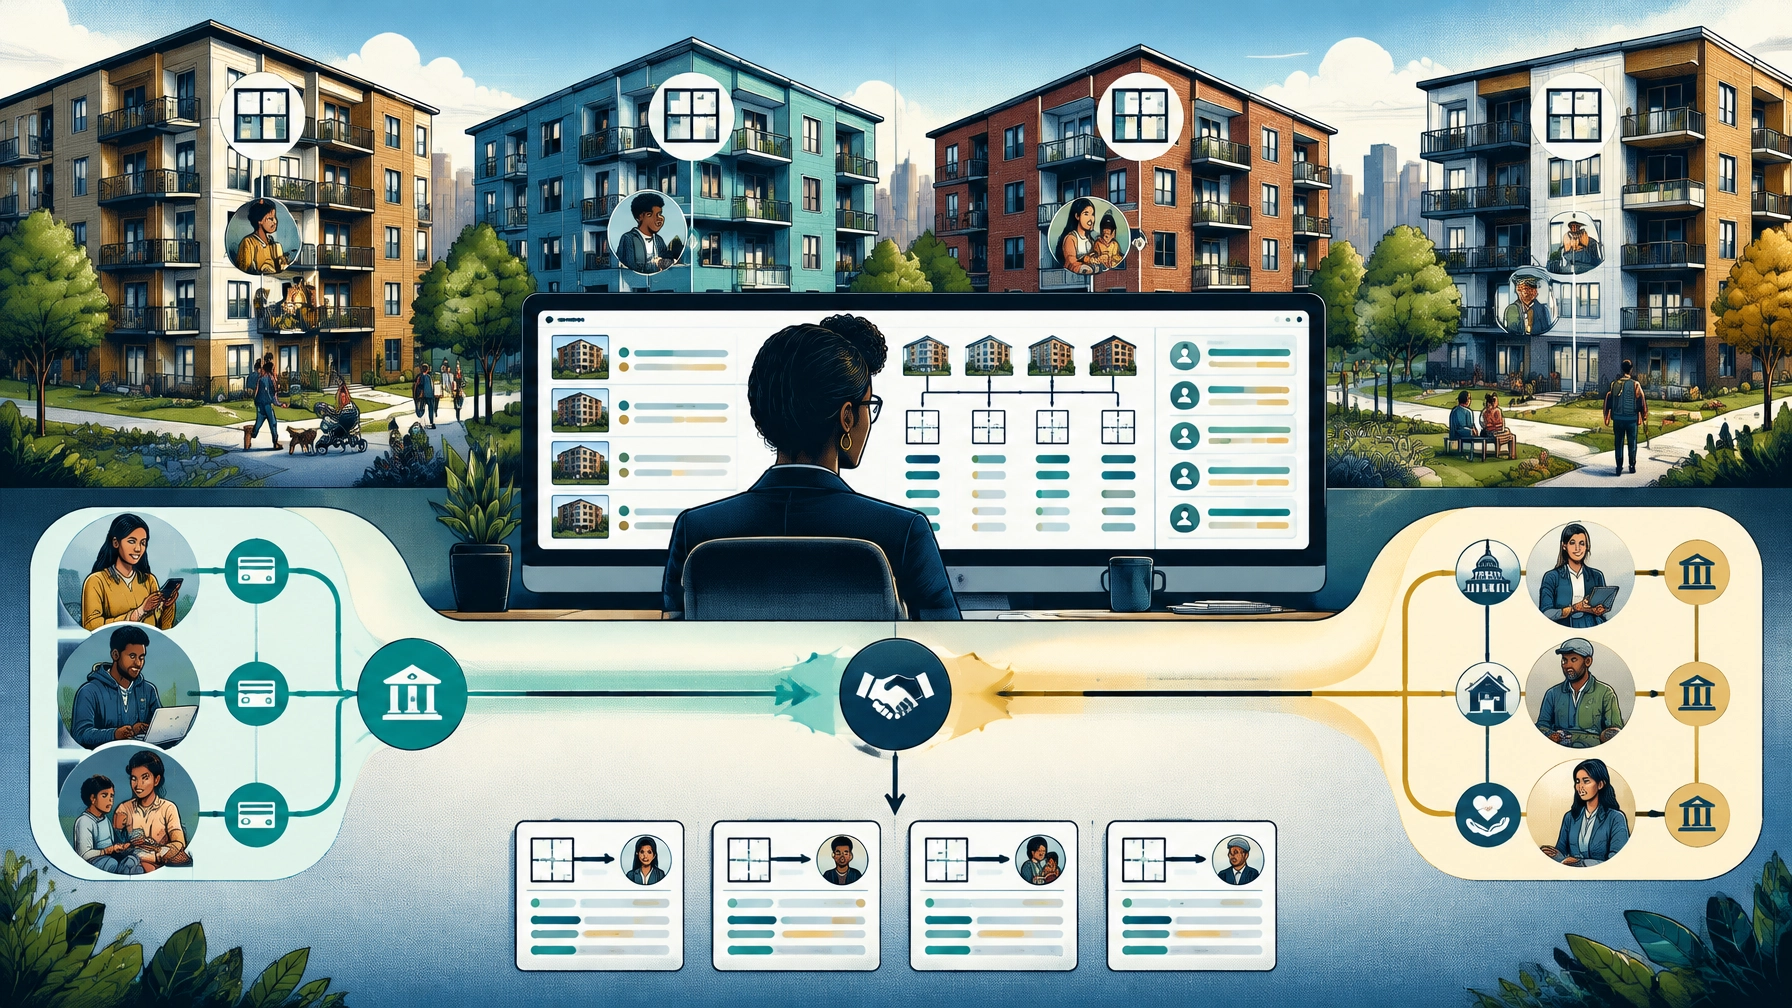
Multifamily Apartment Payment Processing in 2026: Large-Portfolio Rent Collection, Subsidized Housing, and Unit-Level Reconciliation
Call 866-305-6454 now to review payment processing for a multifamily portfolio. Multifamily rent collection needs controls at the property, legal-entity, lease, and unit levels. A payment can be approved but still be assigned to the wrong property, payer, or charge. Build the payment flow around the portfolio’s actual ownership and accounting structure. This article focuses…
-
Veterinary Clinic Payment Processing in 2026: Front-Desk Terminal Flow, Wellness Plan Billing, and CareCredit-Style Financing
Call 866-305-6454 now to review veterinary clinic payment processing, gateway integration, and merchant account options. Veterinary practices combine clinical care with retail-style checkout. They may take payment at the front desk, by phone, through a client portal, by text-to-pay, and through recurring wellness plans. Each channel needs clear authorization, accurate records, and a reliable path…
-
Collecting a Vendor’s W-9 Before the First Payment: What the IRS Says About TINs, Backup Withholding and B Notices
What IRS materials say about Form W-9, taxpayer identification numbers, the 24% backup withholding rate and the B-notice process, as general education for finance teams.
-
Same Day ACH Limit Rising to $10 Million: What B2B Payers Should Do Before September 2027
Same Day ACH has been available for business payments for years, but the rule that sets how large a single same-day payment can be is about to change. Nacha’s rules currently cap a Same Day ACH payment at $1 million. A Nacha rule page titled “Increasing the Same Day ACH Dollar Limit to $10 Million”…
-
Gym and Fitness Studio Payment Processing in 2026: Membership Billing, Freeze and Cancel Handling, and Class-Pack Settlement
Call Bridge Capital Partners at 866-305-6454 now to review gym and fitness studio payment processing. Why gym billing is a contracts problem wearing a payments costume A gym payment is not just an authorization request. It is part of an agreement about access, billing frequency, pauses, cancellations, renewals, and refunds. The payment system needs to…
-
ACH Notification of Change (NOC) in 2026: What Originators Must Do and by When
What an ACH Notification of Change is, who sends it, and the six-banking-day originator deadline under Nacha’s rules text.
-
Verifying a Vendor Bank Account Before the First ACH Payment: What Nacha Says About Micro-Entries
What Nacha’s published rules say about Micro-Entries used for ACH account validation, including amount limits, the ACCTVERIFY description, and fraud-detection requirements. General information only, not advice.
-
ACH Return Rate Levels in 2026: What Nacha’s 0.5%, 3% and 15% Thresholds Mean for Originators
Anyone who originates ACH debits, whether a business collecting invoices, a software company billing customers, or a third-party sender processing for others, eventually learns that returns are not just an operational nuisance. Returns are also a quality signal that the ACH Network watches. Nacha, the organization that writes the ACH rules, publishes return rate levels…
-
Early-Pay Discounts and Payment Terms in 2026: How 2/10 Net 30 Works and How to Calculate What It Is Worth
How 2/10 net 30 early-pay discount terms work, the formula for what they are worth, a clearly hypothetical worked example, and how payment method affects the deadline.
-
CCD, CCD+ and CTX: How B2B ACH Payments Carry Remittance Data
Informational only. This article is general education about payment formats, not legal, tax, accounting or financial advice. Confirm requirements with your bank, your ODFI or processor, and qualified counsel before changing how you send or receive payments. When a business pays another business by ACH, the money is only half of what the receiver needs.…
-
Assisted Living and Senior Care Payment Processing in 2026: Private-Pay Billing, Family Guarantors, and Long-Term Care Insurance
Call 866-305-6454 now to review payment processing for assisted living, memory care, and senior care facilities. Senior care billing is not a simple monthly subscription. The resident, family member, fiduciary, insurer, and public-benefit program may all be involved in the same care month. A facility needs a payment record that identifies who paid, what they…
-
Government and Municipal Payment Processing in 2026: Property Tax, Utility Billing, and Court Fee Acceptance
Call 866-305-6454 to review payment acceptance options for a government or municipal operation. Government payment processing connects statutory billing programs, public-facing service channels, payment providers, and finance systems. A transaction may settle successfully while posting to the wrong account. A resident may pay twice while a property transfer is being recorded. A utility customer may…
-
June 2027 ACH Recredit Proposal: 6 Preparation Steps for Originators and Merchants
Call 866-305-6454 to review ACH payment processing and authorization-record procedures. Nacha has proposed a rule change. It has not been adopted. The proposed effective date is June 18, 2027. The deadline to submit comments is December 11, 2026. ACH originators, debt collection agencies, billing businesses, and payment providers should understand what the proposal would, and…
-
ACH Debits Between Businesses in 2026: CCD Entries, Authorization, and Return Windows
What Nacha materials say about corporate (CCD) ACH debits, authorization, R29 returns, and the two-day versus 60-day return windows.
-
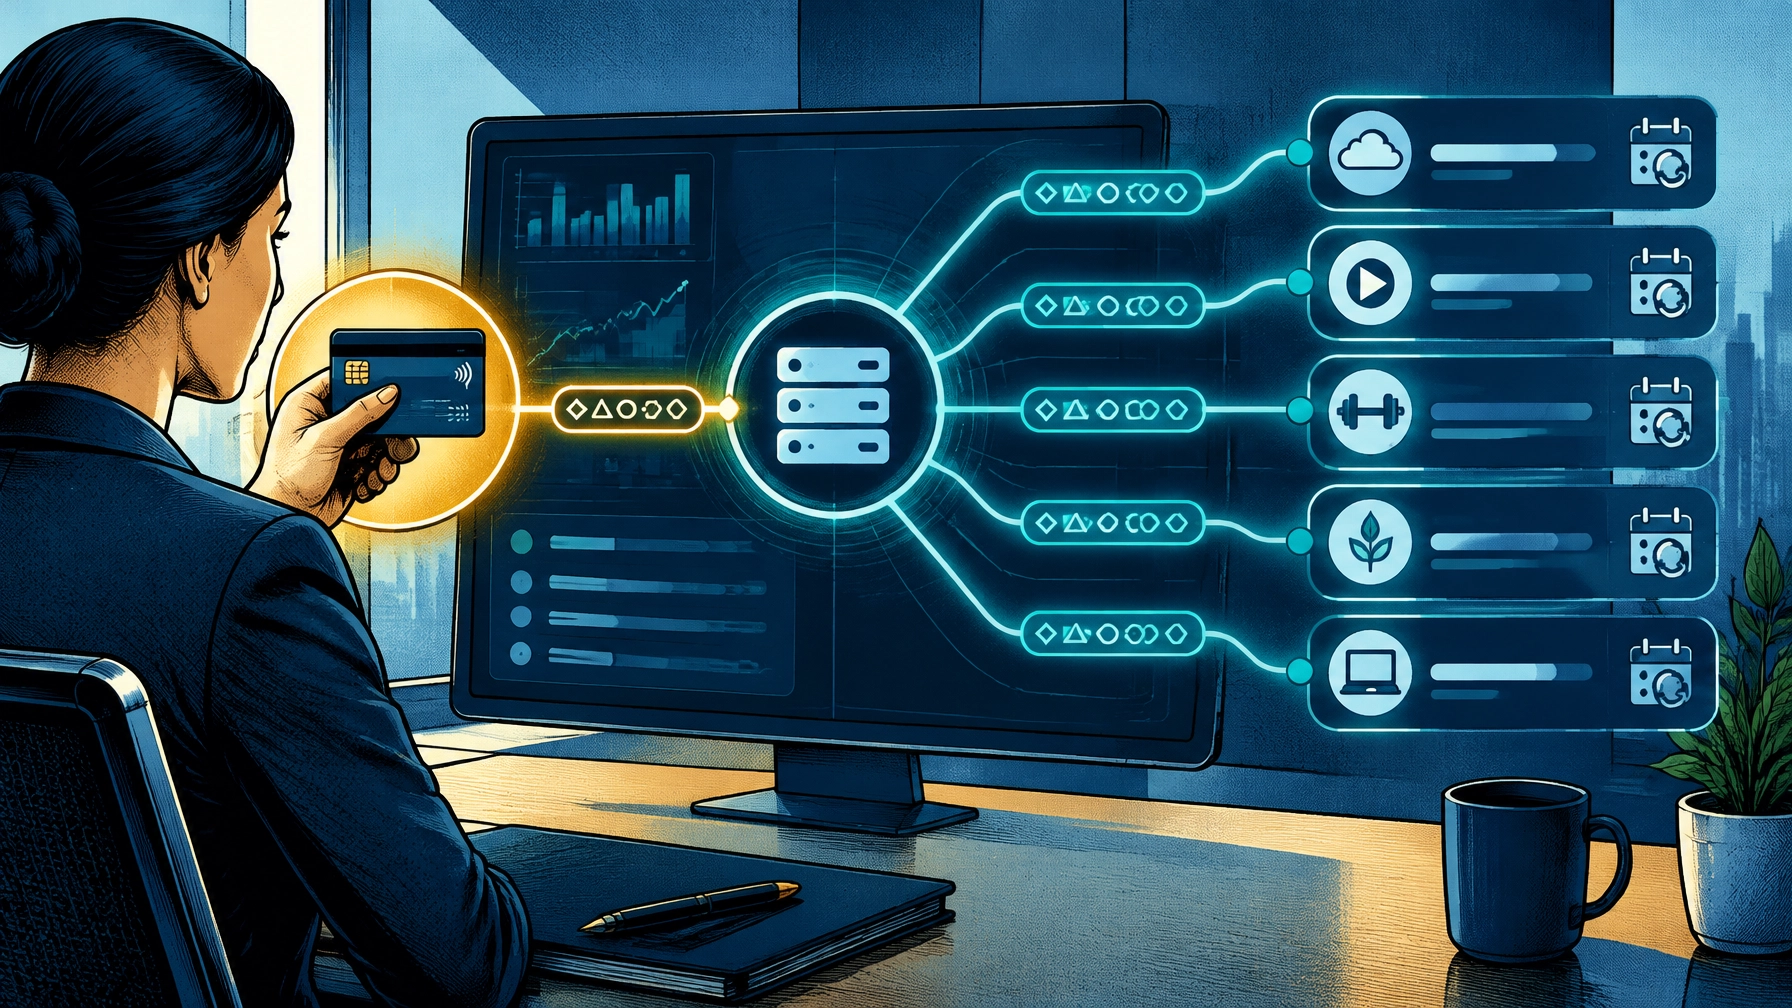
Mastercard TLID Goes Live December 1, 2026: 5 Steps Recurring Billing Merchants Must Complete Before the Deadline
Call Bridge Capital Partners at 866-305-6454 to review your recurring-payment setup. Mastercard’s Transaction Link Identifier (TLID) is a transaction reference intended to connect related payment activity across a transaction’s lifecycle. The December 1, 2026 comply-by date is approaching. Merchants that store cards or run subscriptions should ask their gateway and acquirer how TLID is handled…
-
Regulation CC Funds Availability for Business Deposits in 2026: What the Federal Schedule Says About When Checks and Electronic Payments Can Be Used
This article is general information, not legal, financial, tax, or compliance advice. Bridge Capital Partners does not provide advice on your specific situation. Consult qualified counsel and your financial institution about your account agreements. Anyone who deposits customer payments has asked the same practical question: when can we actually spend this money? For deposits at…
-
Visa 3DS DAF Sunset in 2026: 7 Migration Steps for High-Risk E-Commerce Merchants to Keep 3-D Secure Coverage Active
Call Bridge Capital Partners at 866-305-6454 to review your card-not-present payment processing and confirm your authentication setup. Visa’s Digital Authentication Framework (DAF) 3-D Secure program sunset in September 2026. Check your live payment flow now. Do not assume returning-customer challenge suppression still applies. What DAF 3DS Was and What the Sunset Removes Visa DAF 3DS…
-
Regulation E and Business Accounts in 2026: Why Consumer Payment Protections Often Do Not Reach B2B Transactions
This article is general information, not legal, financial, tax, or compliance advice. Bridge Capital Partners does not provide advice on your specific situation. Consult qualified counsel and your financial institution about your agreements. What consumer protections do and do not reach B2B payments. Business owners often assume that the dispute and refund rights they enjoy…
-
UCC Article 4A and Wire Transfers: What a “Security Procedure” Means for Your Business and Your Bank
How UCC Article 4A treats unauthorized wire payment orders, what a security procedure is, and what B2B finance teams may want to ask their bank. Educational only, not legal advice.
-
The Federal Paper Check Phase-Out: What Treasury Sources Say About Getting Paid Electronically by Government Customers
A summary of Executive Order 14247 and Treasury Fiscal Service guidance on the federal move from paper checks to electronic payments, and what it means for vendors. Informational only.
-
Telehealth Payment Processing in 2026: Card-Not-Present Visits, Membership Care Plans, and HSA-FSA Acceptance
Call Bridge Capital Partners at 866-305-6454 now to review a telehealth payment flow, merchant-account structure, or gateway setup. A virtual visit can lead to several different payment transactions A telehealth appointment is remote. So is the payment only if the patient pays through a portal, app, phone call, or later invoice. Each channel creates different…
-
Check 21 and Remote Deposit Capture in 2026: What Federal Sources Say and What B2B Businesses Should Ask Their Bank
What the Federal Reserve and FDIC say about Check 21, substitute checks and remote deposit capture, and the questions B2B businesses can ask their bank.
-
Nacha Fraud Monitoring Rules in 2026: What Phase 1 and Phase 2 Mean for B2B ACH Originators
Business payments teams that send ACH credits for payroll, vendor payments or refunds now work under Nacha fraud monitoring requirements that took effect in 2026. Nacha’s fraud monitoring amendments took effect in two phases during 2026, and both phases are now in force. This article summarizes what Nacha’s own rule pages say, what the rule…
-
Recalling a B2B Payment in 2026: ACH Reversals, Wire Recalls, and What Finality Means by Payment Type
How reversal, return and recall options differ across ACH, wires, checks and cards, based on Federal Reserve, Nacha, CFPB and FBI IC3 sources.
-
Positive Pay and Check Fraud in 2026: What Federal Sources Say and What to Ask Your Bank About B2B Check Controls
Informational only. A plain-language look at check fraud figures published by FinCEN, what positive pay does and does not cover, and questions to ask your bank.
-
Restaurant and Food Service Payment Processing in 2026: Tip Adjustment, Pay-at-the-Table, and Delivery Settlement
Call 866-305-6454 to review restaurant payment processing, POS configuration, and settlement workflows. Restaurant payments move through different paths. A guest paying at a dining-room table is not the same as a customer ordering online for delivery. Tip adjustments, merchant category codes, debit routing, delivery platforms, PCI scope, and late-night batch closing all affect how those…
-
Same Day ACH Goes to $10 Million in 2027: What the Nacha Rule Change Means for B2B Payments
Informational only. This article is general education about published payment network rules. It is not financial, legal, or tax advice, and it does not recommend any payment method, product, or provider. Confirm requirements with your bank, your processor, and a qualified professional before changing any process. Nacha, the body that writes the rules for the…
-
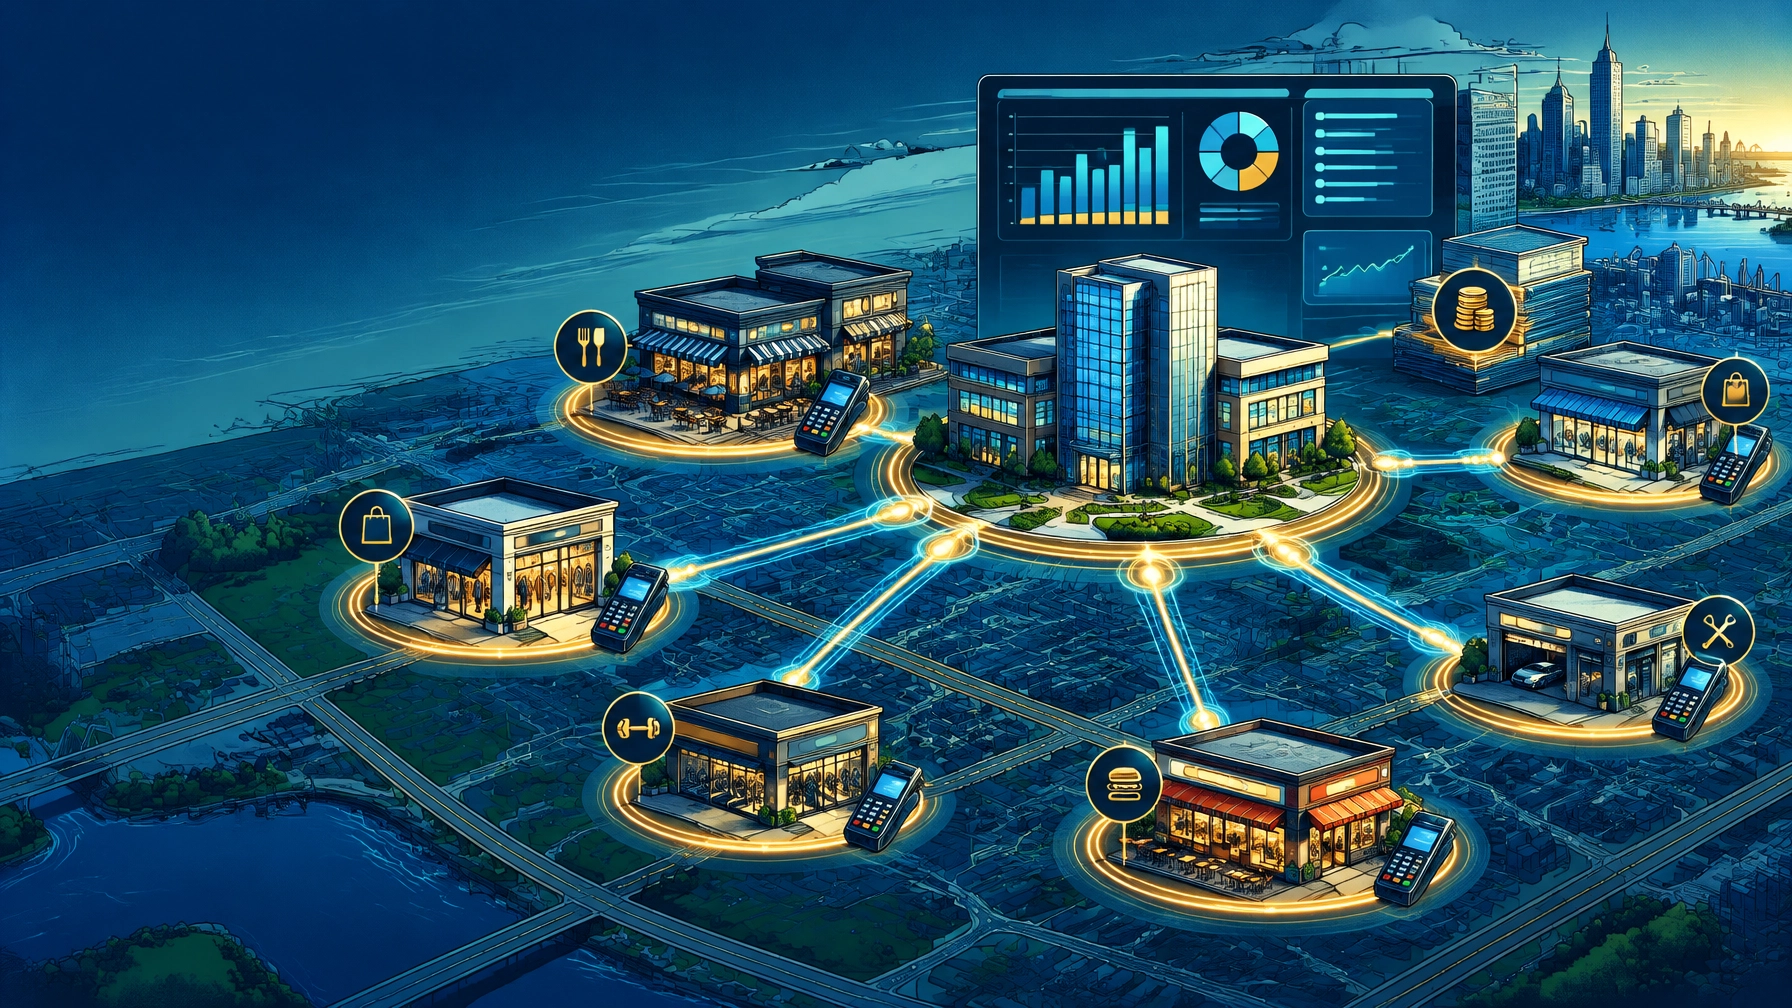
Payment Processing for Franchises in 2026: Multi-Location MID Structures, Royalty Billing, and Centralized Reporting
Call 866-305-6454 now for a franchise payment processing review. Franchise payment processing is not one merchant account multiplied across locations. It is a portfolio structure. Each location may have a different legal owner, physical address, terminal estate, sales mix, settlement account, chargeback profile, and customer-facing descriptor. The franchisor may control the brand, technology, reporting, and…
-
Business Email Compromise and B2B Payments in 2026: What the FBI Reports and the Vendor-Change Controls Finance Teams Use
What the FBI and IC3 report about business email compromise and the verification steps finance teams use for vendor payment changes.
-
Fedwire and ISO 20022 in 2026: What the Wire Message Change Means for B2B Remittance Data and Reconciliation
Wire transfers have long been the default rail for large, time-sensitive business payments in the United States. Since July 2025, the Fedwire Funds Service that carries them has used a different message format, ISO 20022, and that change affects what payment data accompanies a wire. This article explains what changed, what stayed the same, and…
-
Switching Payment Processors in 2026: A Broker-Led Migration Plan for Recurring Billing, Tokens, and Settlement Continuity
title: Switching Payment Processors in 2026: A Broker-Led Migration Plan for Recurring Billing, Tokens, and Settlement Continuityslug: switching-payment-processors-in-2026-broker-led-migration-plan-recurring-billing-tokens-and-settlement-continuitysources: – https://developer.visa.com/capabilities/vts – https://developer.mastercard.com/product/mdes – https://www.pcisecuritystandards.org/standards/pci-dss/ – https://www.nacha.org/rules – https://www.consumerfinance.gov/rules-policy/regulations/1005/ – https://www.federalreserve.gov/paymentsystems/regii-about.htm Call 866-305-6454 now. Contact Bridge Capital Partners to plan a processor migration before recurring billing, stored credentials, settlement timing, or dispute handling are disrupted. Processor…
-
Form 1099-K for Merchants in 2026: What Processors Report and How to Reconcile It
Disclaimer: This article is general information about payment processing and IRS reporting rules. It is not tax, legal, accounting or financial advice, and it does not account for your specific situation. Rules change, so confirm current requirements with the IRS and a qualified tax professional before making decisions. Every January, merchants who take card and…
-
Payment Processing for Nonprofits in 2026: Donation Acceptance, Recurring Giving, and PCI Scope Control
Call 866-305-6454 to review nonprofit payment acceptance, online credit card processing, ACH donations, recurring giving, and PCI scope control. 1. Treat nonprofit payment processing as a control system Nonprofit payment processing is not only a checkout function. It connects: Donation forms. Peer-to-peer campaigns. Crowdfunding pages. Text-to-give programs. Event terminals. Phone donations. Mailed checks. ACH authorizations.…
-
Card-on-File Payments in 2026: Stored Credential Rules, Merchant-Initiated Transactions, Consent and PCI Considerations
Call 866-305-6454 to review card-on-file payment processing, recurring billing, gateway tokenization, and merchant account underwriting. Card-on-file payments let a business save a customer’s payment credential and use it again later. They sit behind subscriptions, membership dues, one-click checkout, invoice autopay, and top-up balances. Card networks treat these payments as a defined framework, and the way…
-
Property Management Payment Processing in 2026: Rent Collection, ACH Debits, and Tenant Payment Portals
Call 866-305-6454 to review property management payment processing, ACH payment processing, gateway options, and merchant account underwriting. Property management payment processing is not a standard retail checkout. The payment flow may include monthly rent, security deposits, application fees, late fees, maintenance charges, owner disbursements, refunds, and multiple residents connected to one unit. The operating model…
-
Insurance Agency Payment Processing in 2026: Premium Financing, Recurring Billing, and ACH for Independent Agents
Call 866-305-6454 to review payment processing, recurring billing, ACH, and merchant account options for an insurance agency. Insurance agencies need payment controls that match the policy lifecycle. A policy may be paid in full, billed in installments, financed through a separate lender, or renewed through recurring ACH drafts. The payer may be the policyholder, a…
-
Card Not Present Payment Processing in 2026: Fraud Controls, Chargeback Defense, and Approval Optimization
Call 866-305-6454 now. Bridge Capital Partners can review your card-not-present payment processing, gateway setup, fraud controls, pricing, and account structure. Card-not-present payment processing covers transactions where the card is not physically presented to the merchant. The customer may pay through a website, mobile application, invoice, phone call, subscription schedule, or remote payment link. The operating…
-
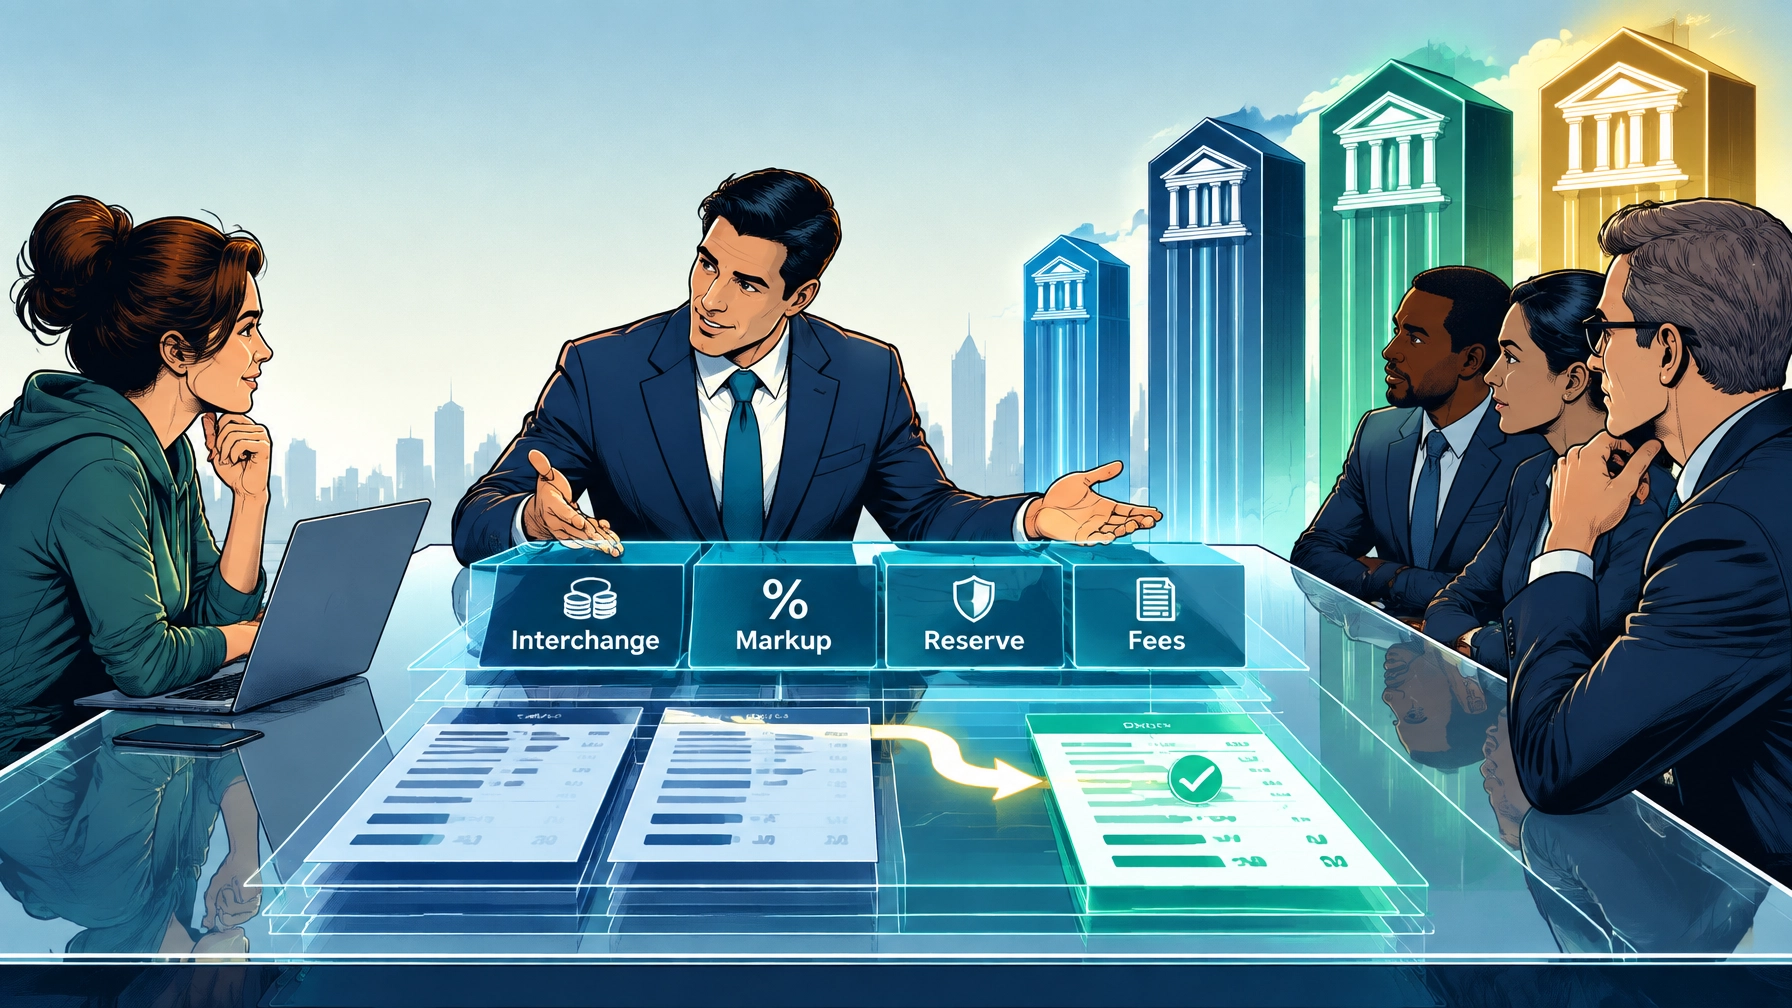
How Merchant Account Brokers Lower Credit Card Processing Rates in 2026: Interchange-Plus Negotiation, Reserve Terms, and What to Compare Before You Sign
Call Bridge Capital Partners now: 866-305-6454.Request a written comparison of interchange-plus pricing, reserve terms, gateway costs, and contract conditions before signing. A merchant account broker can lower payment costs by creating competition between acquiring banks. The broker does not negotiate Visa or Mastercard interchange. The broker negotiates the costs added around interchange. Those costs include:…
-
Visa VAMP and Mastercard Excessive Chargeback Program in 2026: Thresholds, TC40 vs. TC15, and What High-Risk Merchants Must Do
Call Bridge Capital Partners at 866-305-6454 now for high-risk merchant account support and card not present payment processing guidance. High-risk merchants face two separate network-monitoring structures in 2026: Visa’s Acquirer Monitoring Program, or VAMP. Mastercard’s Excessive Chargeback Program, or ECP. The programs do not use the same formula. They do not use the same thresholds.…
-
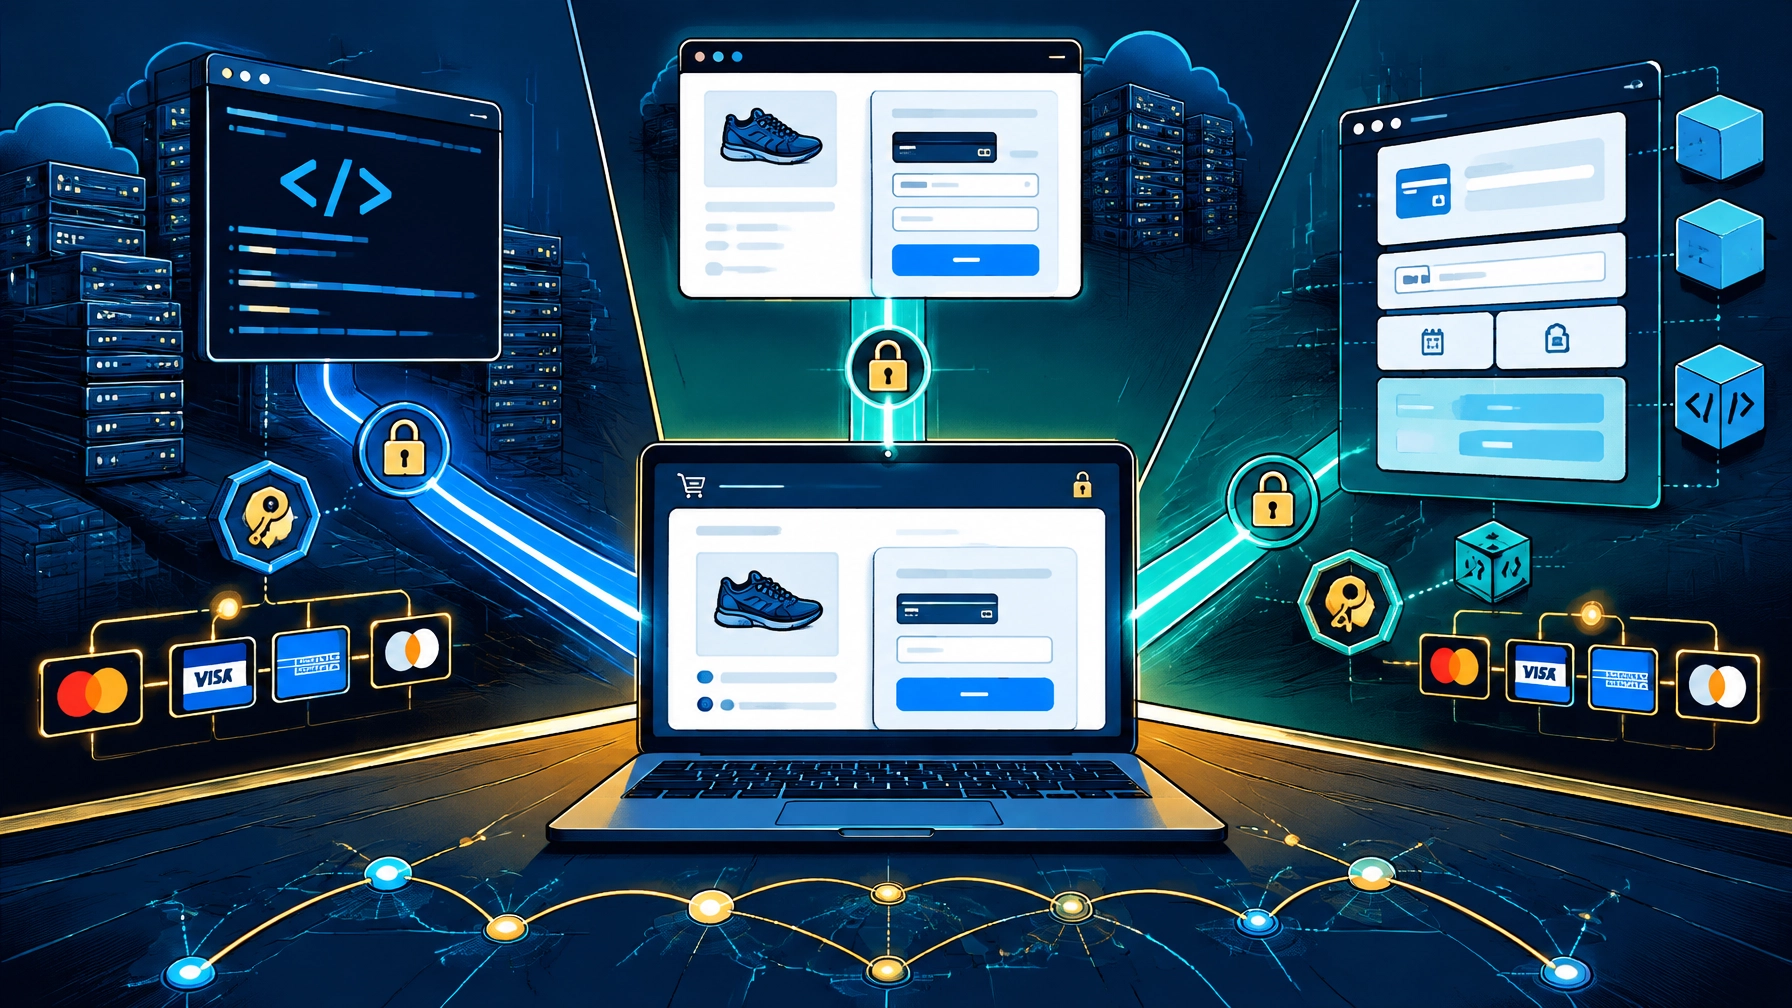
Payment Gateway Integration in 2026: API, Hosted Checkout, and SDK Options Compared for E-Commerce Merchants
Call Bridge Capital Partners now: 866-305-6454 Choose the payment gateway integration path before development begins. The decision affects: Checkout control. Conversion management. Development time. Online credit card processing. Recurring billing. Refund handling. Fraud controls. PCI DSS scope. Merchant account underwriting. Long-term operating costs. Three options dominate e-commerce builds in 2026: Direct API integration. Hosted checkout…
-
Credit Repair and Document Prep Merchant Accounts in 2026: High-Risk Underwriting, Compliance, and Chargeback Control
Need a high risk merchant account now? Call Bridge Capital Partners at 866-305-6454. Credit repair and document preparation businesses face elevated payment risk. The risk comes from four areas: Strict consumer-protection laws. Advance-fee restrictions. Card-not-present enrollment. High dispute and cancellation exposure. A standard payment account may not fit this business model. An account can be…
-
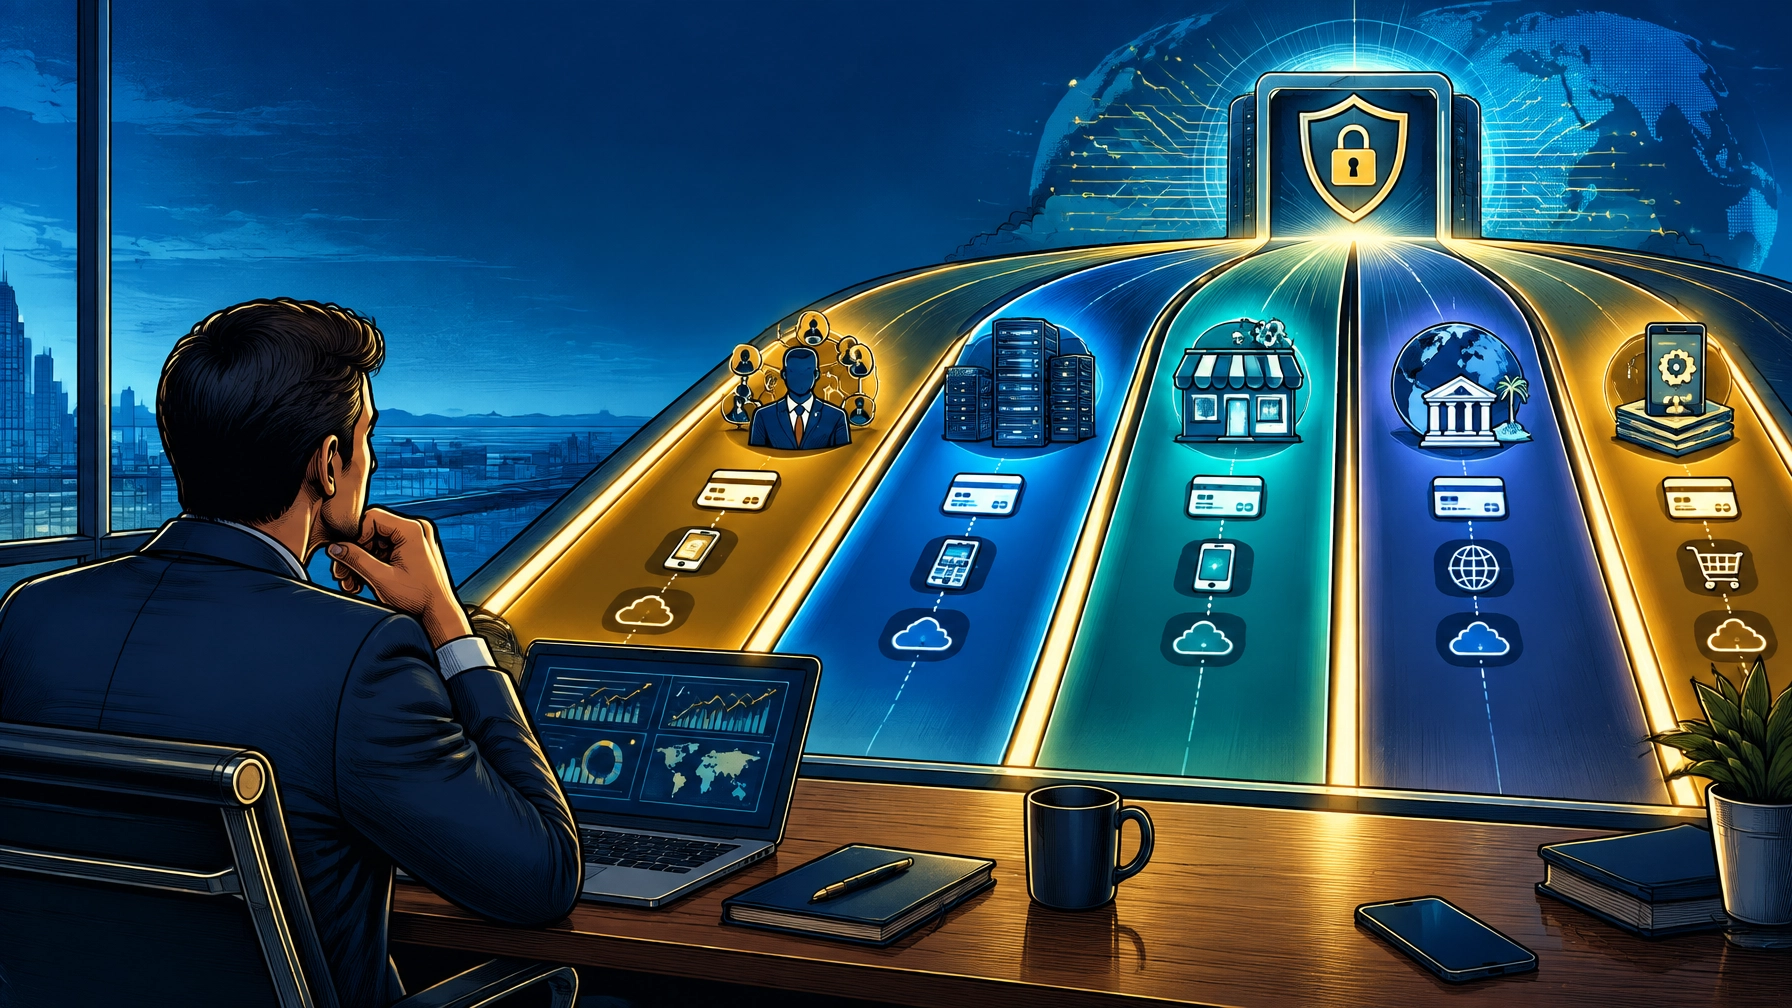
How to Choose the Best High-Risk Merchant Account Provider in 2026: Five Provider Models Compared
Call 866-305-6454 now for a high-risk merchant account review. A high-risk merchant account provider must do more than approve an application. The provider must support your industry, transaction method, customer geography, volume, reserve needs, and chargeback controls. Compare the provider model before comparing rates. A low advertised rate does not help if the account is…
-
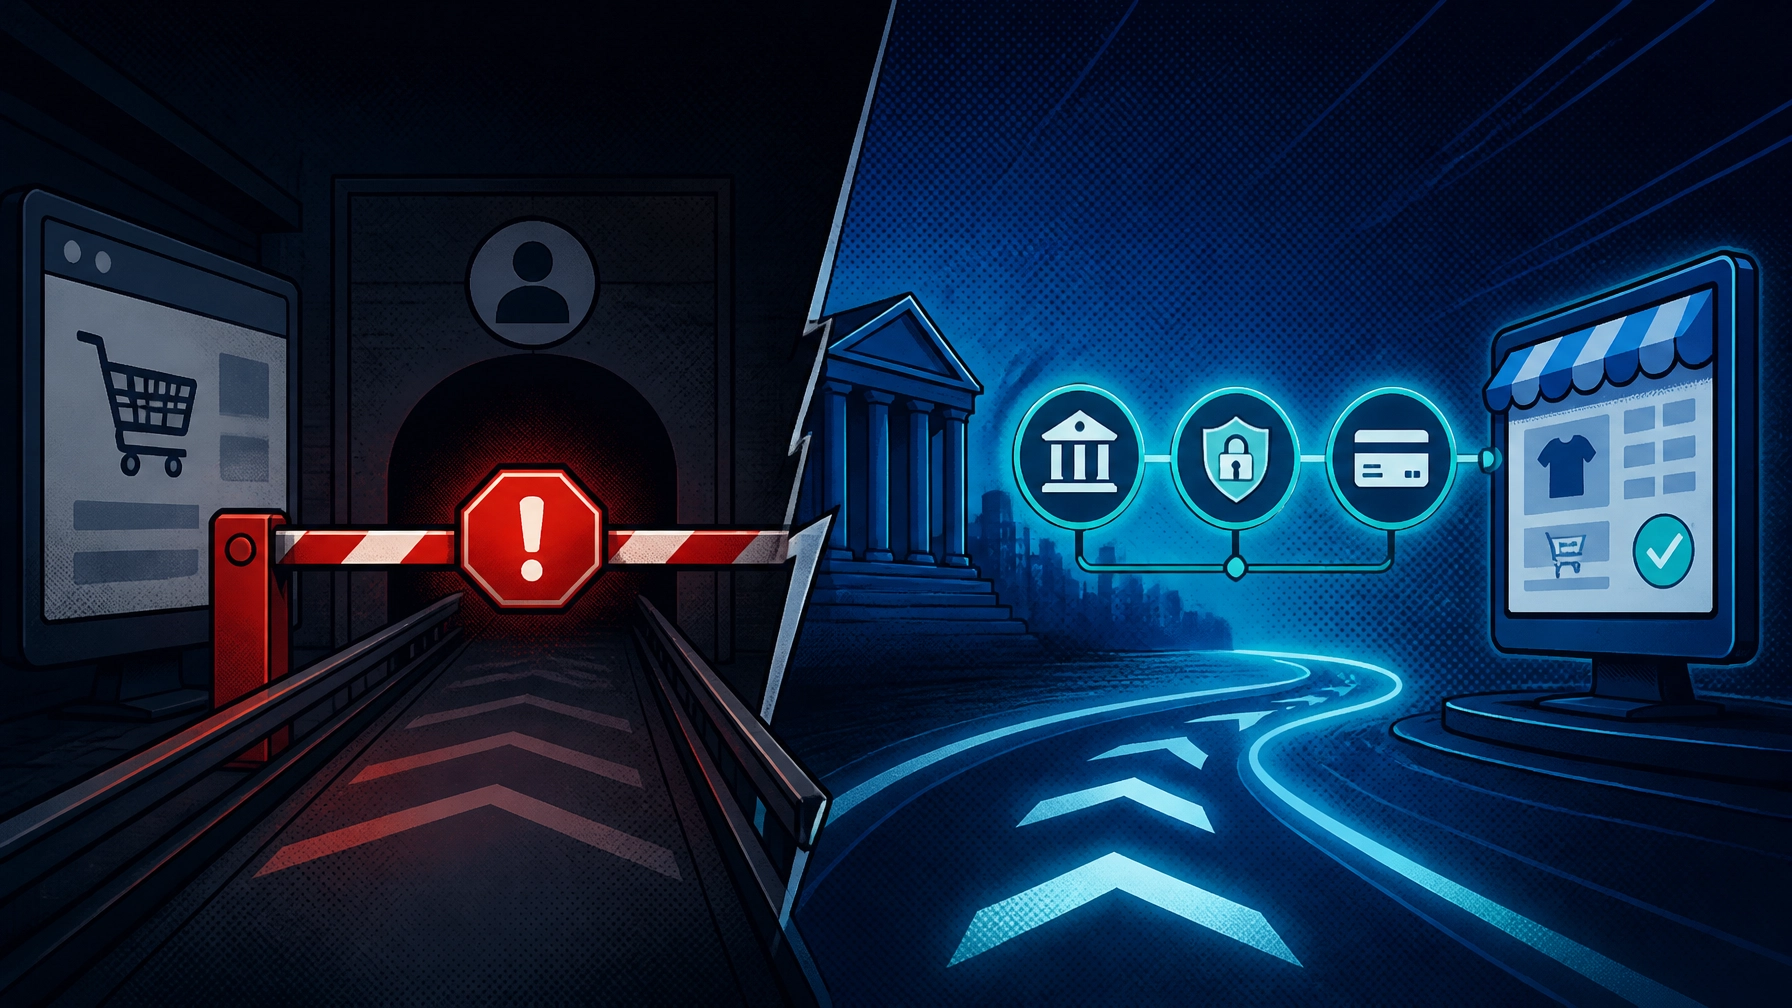
High-Risk Merchant Account vs. Traditional Processing in 2026: E-Commerce Application Decisions, Costs, and Risk Controls
Call 866-305-6454 now for a high-risk processing review. E-commerce businesses with elevated chargeback exposure, recurring billing, regulated products, large transactions, or international sales may not fit a traditional payment processor. The wrong account can create serious operating problems: Frozen funds. Sudden termination. Reserve increases. Gateway disruption. Lost customer payments. Network monitoring exposure. Difficulty securing a…
-
E-Cigarette and Vape Merchant Accounts in 2026: High-Risk Underwriting, Compliance, and Chargeback Control
Call 866-305-6454 now for a vape merchant account review. E-cigarette and vape businesses face stricter payment underwriting in 2026. The risk comes from four areas: Federal tobacco regulation. State and local licensing. Card-network monitoring. Card-not-present chargebacks. A standard payment aggregator may decline the business. An existing account may be frozen after the processor identifies vape…
-
ACH Payment Processing vs. Real-Time Payments in 2026: Cost, Speed, and Settlement Tradeoffs for Small Business Cash Flow
Call 866-305-6454 now for a payment processing review.Compare ACH costs, settlement timing, gateway options, and account requirements before changing your payment flow. Small businesses do not need the fastest payment rail for every transaction. They need the right rail for each cash-flow event. ACH payment processing remains practical for invoices, payroll, recurring debits, and vendor…
-
Mobile Payment Processing for Field Service and Contractor Businesses in 2026: On-Site Card Acceptance, Invoicing, and Merchant Account Options
Call Bridge Capital Partners now at 866-305-6454 for mobile payment processing, card-not-present payment processing, gateway integration, and contractor merchant account options. Field-service businesses collect payments in changing environments. A plumber finishes an emergency repair at a residence. An HVAC technician replaces a failed component. An electrician completes a panel upgrade. A landscaper finishes a scheduled…
-
Online Gaming and Fantasy Sports Merchant Accounts in 2026: High-Risk Underwriting, Compliance, and Chargeback Control
Call Bridge Capital Partners now at 866-305-6454 to discuss a compliant payment structure for online gaming or fantasy sports. This article provides payment-processing information. It does not provide legal advice. Confirm product legality, licensing, age rules, and market access with qualified gaming counsel and the applicable regulator before processing transactions. Online gaming and paid fantasy…
-
Firearms and Ammo Merchant Accounts in 2026: High-Risk Underwriting, Compliance, and Payment Solutions
Call 866-305-6454 now for a firearms and ammunition payment-processing review. Firearms and ammunition merchants require payment infrastructure built for regulated commerce. Standard payment aggregators may decline the business, restrict products, hold funds, or terminate service after underwriting changes. A specialized high risk merchant account gives the business a clearer path to card acceptance. Approval still…
-
Travel and Tour Merchant Accounts in 2026: High-Risk Processing, Rolling Reserves, and Chargeback Control
Call Bridge Capital Partners now at 866-305-6454 for a travel and tour payment review. Travel agencies, tour operators, destination services, cruise sellers, ticket brokers, and online travel businesses often need a high risk merchant account. The risk comes from the payment timeline. A customer may pay months before a flight, hotel stay, cruise, excursion, or…
-
ACH Payment Processing for Small Business in 2026: B2B Invoicing, Recurring Payments, and Same-Day Settlement
Call 866-305-6454 to review ACH payment processing for your business. ACH payment processing gives small businesses a bank-to-bank payment option for invoices, subscriptions, memberships, retainers, and high-value transactions. It can reduce reliance on card payments. It can also support predictable recurring billing. ACH is not the same as a card transaction. It uses the Automated…